
Disclaimer: I am a blogger and an investor, not a SEBI-registered investment adviser. What I share here comes from my own learning since 2021. Please treat it as information, not personal financial advice.
“Saving? On ₹25,000? First let the month end.”
I hear some version of this a lot. And honestly, it makes sense. Rent, food, travel and sending some money home can finish ₹25,000 very fast.
But here is a fact worth knowing. As per MoSPI’s Periodic Labour Force Survey, the average regular salaried worker in India earned ₹21,285 a month in 2025. So if you earn ₹25,000, you are already above the national average for salaried jobs. Millions of people save something on less.
Quick answer: To save money on a ₹25,000 salary in India, start by saving 10% (₹2,500) on salary day through an automatic RD or SIP, keep rent within about 25% of income, build a small emergency fund first, and raise your savings by half of every increment. Even ₹2,500 a month can grow to about ₹1.78 lakh in five years in a post office RD.
Why Small Savings Matter More Than You Think
Saving ₹2,500 a month does not feel like much. But it does three things that matter.
First, it builds the habit. The person who saves ₹2,500 at ₹25,000 usually saves ₹10,000 at ₹60,000. The person who waits for a “bigger salary” usually keeps waiting.
Second, it protects you. With retail inflation at 5.54% and food inflation at 7.74% in September 2026, one unexpected bill can push a tight budget into a loan.
Third, it compounds. Small amounts invested for many years grow into real money. More on that below.
You are not alone in starting small, either. AMFI data shows around 63 lakh new SIPs were registered in September 2026 alone, and many of them are small monthly amounts.
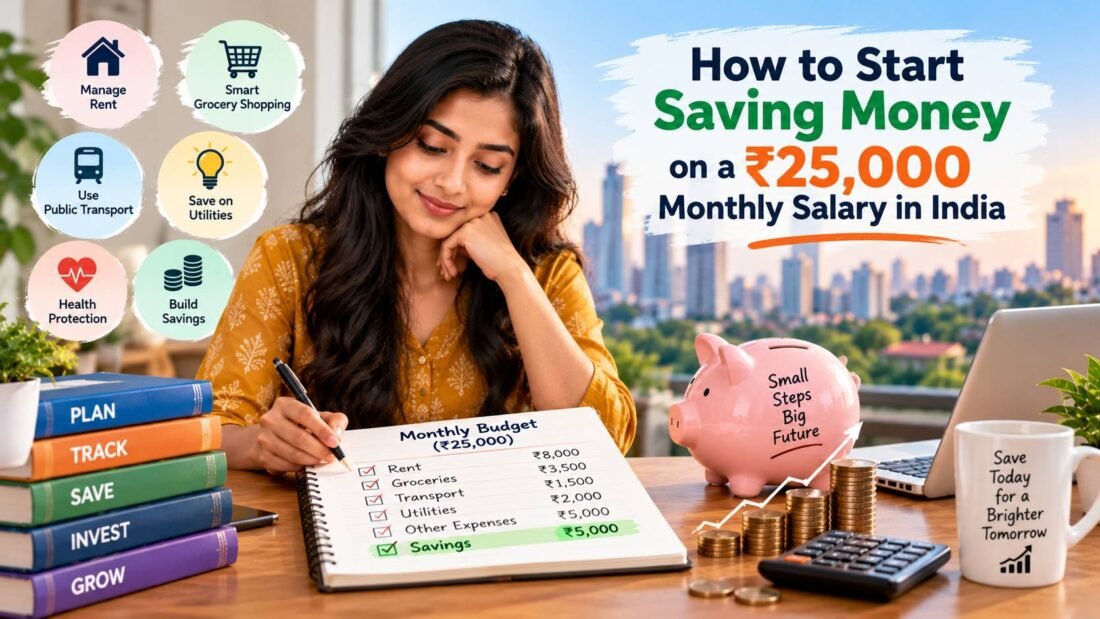
A Realistic Budget for a ₹25,000 Salary
This sample assumes a single person living in shared accommodation in a tier-2 city and sending some money home. Change the numbers to match your life.
| Category | Amount | Share |
|---|---|---|
| Rent (shared flat or PG) | ₹6,000 | 24% |
| Food and groceries | ₹5,000 | 20% |
| Transport | ₹1,500 | 6% |
| Mobile and internet | ₹500 | 2% |
| Money sent home | ₹3,000 | 12% |
| Health insurance (monthly share) | ₹700 | 3% |
| Personal and fun | ₹2,500 | 10% |
| Miscellaneous | ₹800 | 3% |
| Emergency fund | ₹2,500 | 10% |
| RD or SIP | ₹2,500 | 10% |
| Total | ₹25,000 | 100% |
This plan saves 20%. If that is too tight right now, start with 10% and grow it. Starting matters more than the starting amount. For a fuller method, see our monthly budget guide.
Step 1: Save First, Spend Later
The biggest change you can make costs nothing. Move your savings out on the day your salary arrives.
Set up a recurring deposit or SIP with a debit date one or two days after salary credit. Once the money leaves your main account, you plan the month with what remains. You stop “trying” to save and simply save.
I have learned this from my own investing since 2021. When I once stopped a portion of my SIPs early, the money did not go anywhere useful. It just got absorbed into regular spending. Automation protects you from your own tired, end-of-month decisions.
Step 2: Build a Small Emergency Fund First
On a ₹25,000 salary, one hospital visit or a phone repair can wreck the month. So your first savings goal is a buffer, not returns.
Aim for ₹15,000 to ₹20,000 first. At ₹2,500 a month, you will get there in six to eight months. After that, keep building towards three to six months of essential expenses over time. Our emergency fund guide shows how to calculate your target.
Keep this money in a separate savings account or a short FD, not in stocks.
Step 3: Pick a Simple Place for Your Savings
You do not need ten products. One or two simple options are enough at this stage.
| Option | Minimum | Rate or Return (Oct to Dec 2026) | Good For |
|---|---|---|---|
| Post Office 5-year RD | ₹100 a month | 6.7%, fixed | Disciplined saving with no market risk |
| Bank RD | Varies by bank, often ₹100 to ₹500 | Varies by bank and tenure | Short goals of 1 to 3 years |
| Public Provident Fund (PPF) | ₹500 a year | 7.1%, set every quarter | Long-term savings with tax benefits |
| Mutual fund SIP | Often ₹100 to ₹500 a month | Market-linked, not guaranteed | Goals more than 5 years away |
The government kept small savings rates unchanged for October to December 2026, so PPF stays at 7.1% and the post office 5-year RD at 6.7% for this quarter. Scheme details are on the India Post website.
What ₹2,500 a Month Can Become
Here is how ₹2,500 a month can grow. The RD figure uses the current 6.7% rate. The SIP figures assume a 10% yearly return purely as an example. Real mutual fund returns can be higher or lower, and they are never guaranteed.
| Option | Period | You Invest | Approximate Value |
|---|---|---|---|
| Post Office RD at 6.7% | 5 years | ₹1,50,000 | About ₹1.78 lakh |
| SIP at an assumed 10% | 5 years | ₹1,50,000 | About ₹1.95 lakh |
| SIP at an assumed 10% | 10 years | ₹3,00,000 | About ₹5.16 lakh |
| SIP at an assumed 10% | 15 years | ₹4,50,000 | About ₹10.45 lakh |
Look at the last row. Over 15 years, more than half the final value comes from growth, not from your own deposits. That is the reason to start early, even with a small amount. Our post on SIP vs lump sum explains how SIPs work.
Step 4: Cut the Costs That Hurt the Most
On a small salary, saving ₹100 on coffee matters less than saving ₹2,000 on rent. Focus on the big three.
- Rent: Try to keep it under about 25% of income. Sharing a flat or living a little farther from the office can free up thousands.
- Food: Cooking most meals and carrying lunch is the biggest saver for most young earners. Eating out is getting expensive too. Inflation for restaurants and accommodation services was 9.36% in September 2026.
- Transport: Metro, bus or a shared commute usually costs much less than daily cabs or autos.
After these, check small leaks like unused subscriptions and frequent food delivery.
Step 5: Grow Your Savings With Every Raise
Your salary will not stay at ₹25,000 forever. The real test is what you do when it rises.
A simple rule: when you get a raise, put half of the increase into savings. If your salary goes from ₹25,000 to ₹28,000, raise your SIP or RD by ₹1,500 and enjoy the other ₹1,500.
Many SIPs also allow a “step-up” option that increases the amount automatically every year.
Step 6: Keep Learning, Slowly
One habit that has helped me a lot is regular learning. Reading about money, following financial news and understanding how products work.
You do not need to become an expert. Just 15 minutes a week is enough to slowly understand PPF, mutual funds, insurance and taxes. That knowledge protects you from bad products and big mistakes later.
Mistakes to Avoid on a Small Salary
- Taking a personal loan or credit card EMI for a phone or gadget
- Skipping health insurance to save a few hundred rupees
- Putting emergency money in stocks
- Following “quick money” trading tips on social media
- Waiting for a higher salary before starting to save
Conclusion
Saving on a ₹25,000 salary in India is not about big sacrifices. It is about saving a fixed amount first, keeping rent and food costs in check and letting time do the heavy lifting.
Start with ₹2,500 if you can, or even ₹1,000 if that is what works today. Build a small emergency fund, choose one simple savings option and increase it with every raise. The amount will grow. More importantly, so will the habit.
Frequently Asked Questions
How much should I save from a ₹25,000 salary?
Try to save at least 10%, which is ₹2,500 a month. If your rent and other fixed costs are low, aim for 20% (₹5,000). If even 10% is hard right now, start with a smaller amount and increase it as your salary grows.
Is ₹25,000 a good salary in India?
It is above the national average for regular salaried workers, which was ₹21,285 a month in 2025 according to MoSPI's PLFS report. How comfortable it feels depends heavily on your city, rent and family responsibilities.
Where should I invest ₹2,000 a month as a beginner?
For goals within five years, a bank or post office RD is simple and safe. For goals beyond five years, a mutual fund SIP may suit you if you accept market ups and downs. Build a small emergency fund before taking market risk.
Can I start a SIP with ₹500?
Yes. Many mutual fund schemes accept monthly SIPs starting at ₹500, and some allow as little as ₹100. Check the minimum amount on the scheme's official page before investing.
Is PPF good for a low salary?
PPF can work well because the minimum deposit is only ₹500 a year, the rate is government-set (7.1% for October to December 2026) and it offers tax benefits. The catch is a 15-year lock-in, so it suits long-term savings, not emergencies.
How do I save money if I send most of my salary home?
Fix the amount you send home and plan it like rent. Then save even a small fixed amount, such as ₹500 to ₹1,000, on salary day. A small but steady habit is still better than none, and you can increase it later.